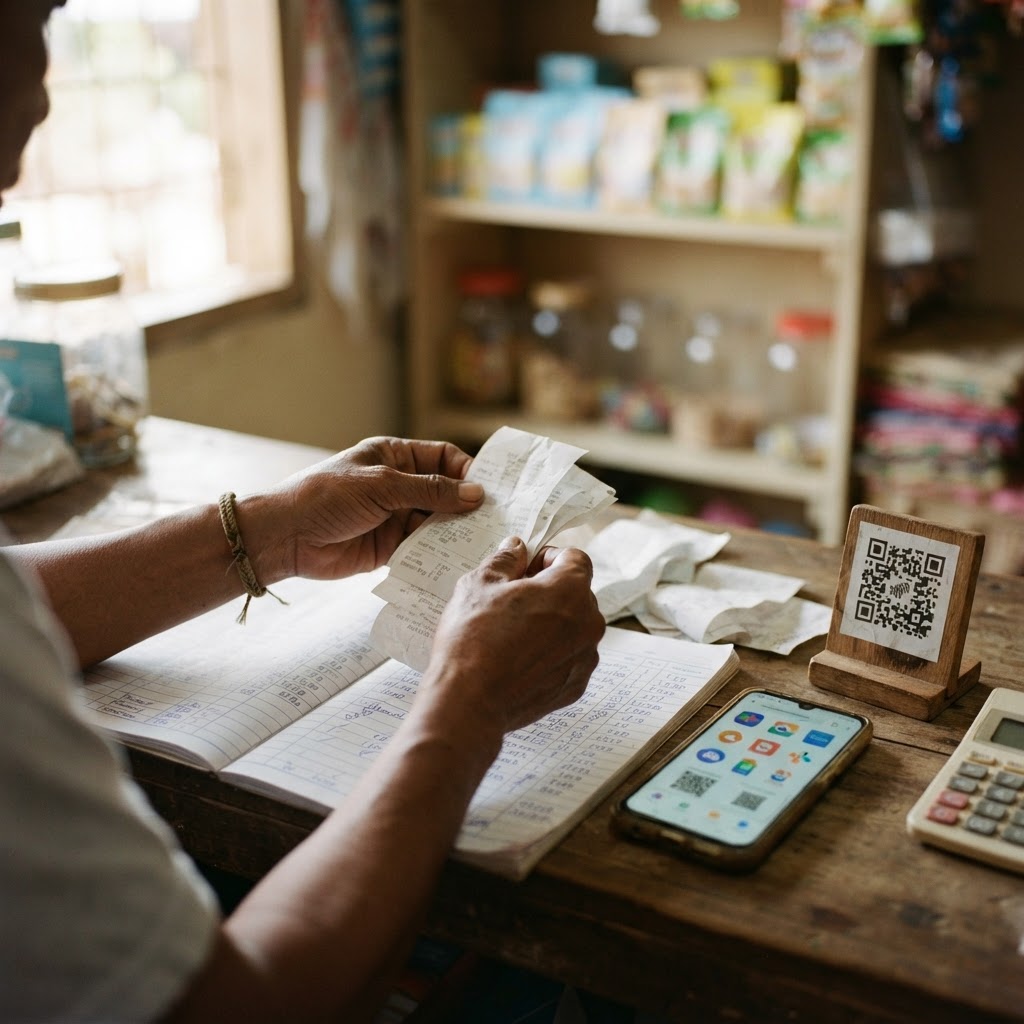
A decade ago, a small business owner in the Philippines mostly dealt with cash and maybe a bank deposit slip. Today, the same owner might accept a bank transfer, two different e-wallets, a QR code scan, cash on delivery, and a marketplace payout that lands a week later, minus a fee nobody fully explained.
Each of these channels was adopted because it solved a real problem. QR payments reduced the friction of carrying cash. E-wallets let customers pay instantly from their phones. Marketplaces opened access to buyers an owner would never have met otherwise. Individually, each addition made sense.
Collectively, they created something nobody quite planned for: a business whose money now arrives through five or six separate doors, each with its own ledger, its own delay, and its own blind spot. The convenience that digital payments promised customers has, in many cases, become a quiet administrative burden for the business owner receiving them.
The Promise That Didn't Quite Deliver
The pitch behind digital payments was always efficiency. No more counting cash at the end of the day. No more trips to the bank. No more disputes about whether a customer actually paid.
That promise holds true at the transaction level. A single QR payment is faster and cleaner than a cash exchange. A single marketplace sale is easier to process than a walk-in haggling over change.
But business owners don't experience money one transaction at a time. They experience it in aggregate, at the end of the day, the week, or the month, when they need to answer a much harder question: how much did I actually make, and where is that money right now?
This is where digital payments quietly shifted the burden. The convenience is front-loaded, experienced by the customer at the point of sale. The cost is back-loaded, experienced by the owner later, when all those separate payment trails need to be pulled together into one coherent picture.
Why More Channels Means More Fragmentation
Every payment channel a business accepts is, in effect, a separate bank account with its own rules. Funds in an e-wallet aren't immediately the same as funds in a bank account. Marketplace earnings often sit in an internal balance before a payout is triggered. Cash on delivery is collected by a rider or staff member before it even reaches the owner.
Each of these channels also has its own timing. Some settle instantly. Some settle in a few days. Some settle on a weekly or biweekly schedule tied to a platform's internal cycle, which the business owner does not control and often cannot predict with precision.
The result is that a business's "total sales" for a given day almost never matches its "total cash available" on that same day. The gap between the two isn't theft or error. It's simply the structural reality of money moving through multiple rails at multiple speeds.
For an owner relying on a single notebook or a single mental tally, this gap becomes invisible until it causes a problem — a missed supplier payment, a payroll shortfall, a moment of genuine confusion about whether the business is actually doing well.
The Hidden Labor of Matching Money to Meaning
Reconciliation is the unglamorous work of matching a payment to what it was actually for. In a cash-only business, this was simple because the money and the transaction happened in the same instant, in the same place.
In a multi-channel digital business, reconciliation means something closer to detective work. A transfer notification arrives with a reference number but no customer name. A marketplace payout arrives as one lump sum covering a dozen separate orders. A QR payment confirmation shows an amount but not which product it was for.
Someone has to sit down and connect these dots: this amount, from this channel, on this date, corresponds to this specific sale. Multiply that across every channel and every day, and reconciliation becomes a recurring task that competes directly with the time an owner would otherwise spend serving customers or improving the business.
Many small business owners underestimate this labor until it has already piled up. Weeks pass. Transactions blur together. By the time someone tries to reconcile everything at once, for tax season or a loan application, the task has become large enough to require outside help, which is itself a cost that didn't exist in a simpler, single-channel era.
The Float Illusion
One subtle effect of multi-channel digital payments deserves particular attention: the gap between what an app shows and what an owner can actually spend.
An e-wallet balance, a marketplace internal balance, and cash sitting with a delivery rider all look like money on a screen or in a pocket. But each carries restrictions. Some require a minimum before a payout can be requested. Some charge a fee to withdraw to a bank account. Some are simply delayed by a platform's internal processing schedule.
The practical effect is that an owner can appear to have healthy total revenue across all channels while having almost no actual liquidity available the moment a supplier invoice or payroll date arrives. This isn't a sign of a failing business. It's a sign that digital payment infrastructure, by design, holds money in transit longer than owners intuitively expect.
Treating every balance shown on a screen as equally spendable is one of the quieter ways digital-era small businesses get caught short, even when their underlying sales numbers look fine.
What This Looks Like for Filipino Small Businesses
The fragmentation problem is especially visible for Filipino micro and small businesses, many of which accept a wide mix of payment methods precisely because their customer base expects that flexibility. A home-based food business might take bank transfers from regular customers, e-wallet payments from first-time buyers, and cash on delivery for orders placed through a social media page. A reseller might combine marketplace sales with direct messages and walk-in pickups.
This flexibility is good for sales. Customers pay however is easiest for them, which removes friction at checkout. But it means the owner inherits all the reconciliation complexity described above, usually without any formal system to manage it, because the business grew organically rather than being designed around a single payment rail from the start.
The owners who manage this well tend to share one habit: they don't wait until tax time or a cash crunch to look at the full picture. They build a routine, even a simple one, for pulling every channel's numbers into one place on a regular basis.
Building a Reconciliation Habit Before You Need One
The fix for payment fragmentation isn't choosing fewer channels — that often means losing customers who prefer a specific payment method. The fix is building a lightweight habit that keeps the fragmentation from becoming invisible.
A few practical starting points:
- Set a fixed day each week to total every channel separately, then compare that total against what actually landed in a usable bank account. The gap itself is useful information.
- Treat marketplace and e-wallet balances as "pending," not "available," until they've actually been withdrawn. Plan expenses around available cash, not displayed balances.
- Keep a simple running note of which channel each sale came through, even a basic tally, so that a lump-sum payout can later be traced back to specific transactions.
- Separate personal and business use within each payment channel wherever the platform allows it, so personal transfers don't get mixed into business reconciliation.
- When a channel's payout schedule is unpredictable, build a buffer into cash flow planning rather than assuming money will arrive exactly when expected.
None of these require new tools or spending. They require treating reconciliation as a standing task rather than an emergency response.
The Real Shift Digital Payments Created
Digital payments did not make money simpler. They made money faster, more flexible, and more accessible to customers — and in doing so, shifted complexity from the moment of the transaction to the moment of the accounting.
For a small business owner, the practical lesson isn't to resist digital payment channels. Customers will keep choosing whichever method is easiest for them, and businesses that accommodate that flexibility generally sell more.
The lesson is to stop assuming that more payment channels automatically means a clearer financial picture. It usually means the opposite, unless someone deliberately builds the habit of pulling the picture back together. In a digital economy where money arrives from more directions than ever, the owners who stay in control aren't the ones with the most payment options. They're the ones who never lose track of where every peso actually is.