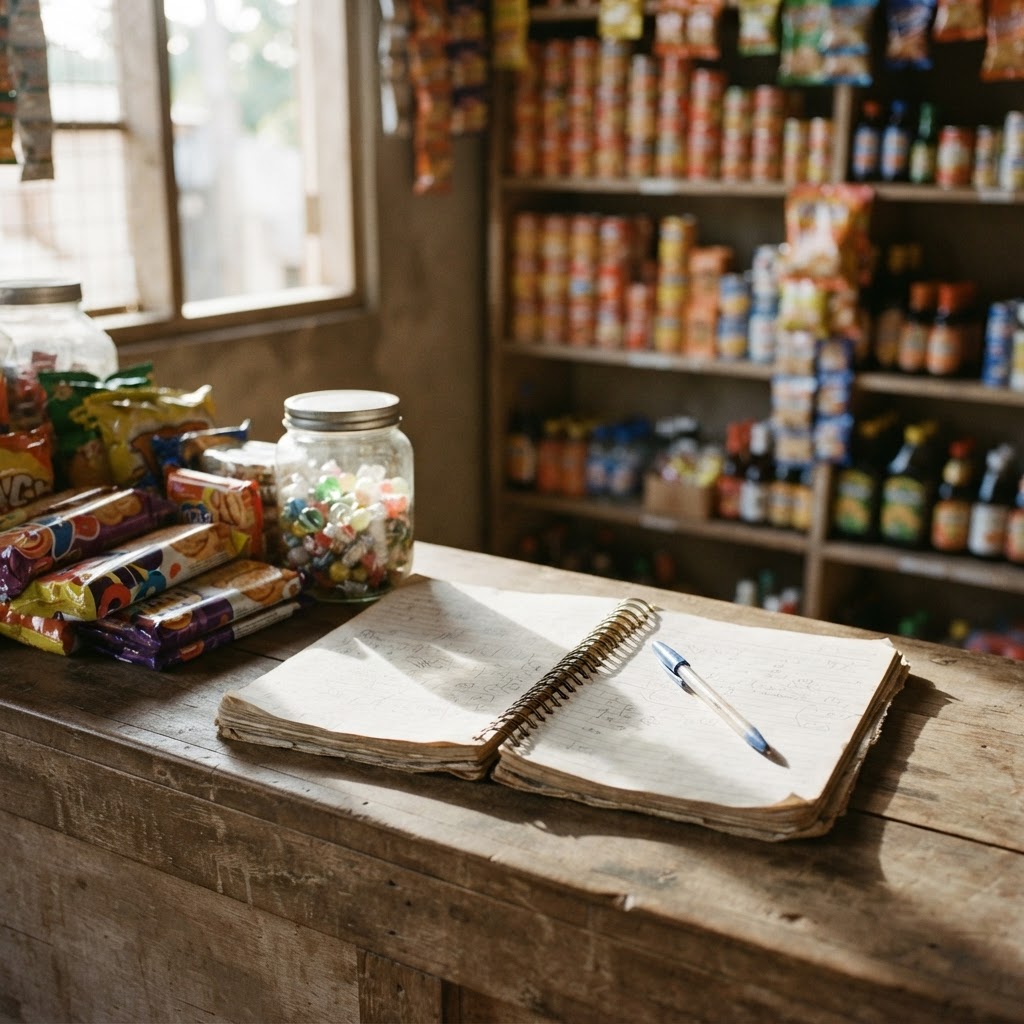
Walk into almost any sari-sari store in the Philippines and you will likely see it: a tattered notebook tucked beside the register, filled with names, small sums, and running tallies. This is the lista — the informal credit ledger that lets regular customers buy now and pay later, sometimes by the day, sometimes by the payday, sometimes whenever money comes in.
It looks like a minor convenience. It is actually one of the clearest windows into how trust, risk, and loyalty function in Philippine commerce — and the lessons extend far beyond the neighborhood store.
The Notebook That Built Communities
The lista system did not emerge from a business plan. It emerged from necessity. Many households experience income in irregular bursts — a remittance that arrives on a certain date, a harvest, a commission, a daily wage paid at the end of the week. Expenses, meanwhile, happen daily. Someone needs rice, sugar, or a few sachets of instant coffee today, even if the money to pay for them arrives tomorrow.
The sari-sari store owner, usually a neighbor who has known the family for years, bridges that gap. There is no interest charged in most cases, no formal contract, no credit score. There is only a name, an amount, and an understanding that it will be settled eventually.
What makes this system remarkable is not its informality. It is how well it works despite that informality. Store owners rarely lose significant money to bad debt, because the system does not rely on paperwork — it relies on relationship. Everyone involved understands that a damaged reputation in a tight-knit community costs more than any unpaid balance ever could.
Why Credit Is Really a Trust Transaction
It is tempting to view the lista as simply informal lending. It is more accurate to describe it as a trust transaction disguised as a financial one.
The store owner is not evaluating income statements. They are evaluating character, consistency, and social standing — whether this customer shows up, whether they have paid before, whether their family has a history of honoring obligations. The amount extended on credit is really a measure of how much social capital a person has accumulated in that community over time.
This is a different kind of underwriting than what formal lenders use, but it is not a weaker one. It simply runs on different inputs: reputation instead of documentation, relationship instead of collateral.
Understanding this distinction matters for any business trying to operate in the Philippines, because it reveals something important about Filipino consumers more broadly: trust is rarely given automatically to an institution. It is extended, carefully and incrementally, to people and relationships that have proven reliable over time.
The Risk Formal Businesses Keep Underestimating
This is where many formal businesses — especially newer entrants — misjudge the market.
A new brand often assumes that a professional storefront, a polished product, or an attractive price is enough to earn a customer's loyalty on the first encounter. In much of the Philippine market, it is not. Consumers are often cautious with unfamiliar businesses, not because they doubt the product, but because they have no relationship history to draw on. There is no notebook, no track record, no neighbor vouching for the seller.
This caution is frequently misread as price sensitivity or slow adoption. In reality, it is often trust sensitivity. A consumer who hesitates to try a new brand, a new payment method, or a new service provider may simply be waiting for enough social proof — a friend's recommendation, a visible track record, a sense that others like them have already taken the risk and been fine.
Businesses that treat this hesitation as a marketing problem to overcome with discounts often miss the real lever: relationship-building and visible reliability over time.
What the Lista System Teaches About Loyalty
The deeper lesson of the sari-sari store is not about credit at all. It is about how loyalty is actually earned in a relationship-driven market.
A few principles stand out:
- Flexibility signals respect, not weakness. The willingness to accommodate a customer's irregular cash flow is read as a sign that the business understands their reality, not that it is desperate for sales.
- Consistency outperforms charisma. A store owner who is reliably there, reliably fair, and reliably patient builds more loyalty over years than any single clever promotion.
- Small, repeated interactions matter more than big, occasional ones. Loyalty in this system is built transaction by transaction, not through a single impressive pitch.
- Trust is local before it is national. People trust the specific person behind the counter before they trust the brand on the signage.
Many Filipino small businesses already operate instinctively this way — remembering a customer's usual order, extending a bit of grace on payment, greeting regulars by name. What the lista makes visible is that this behavior is not a soft or old-fashioned business practice. It is a sophisticated trust-building mechanism that larger, more formal businesses often fail to replicate.
Modern Businesses Borrowing the Old Logic
The underlying structure of the lista has not disappeared — it has simply changed form.
Installment-based payment options, flexible subscription terms, and "pay when you can" arrangements among freelancers and small service providers are all modern descendants of the same idea: extend a measure of trust first, and let reliability earn the rest.
Freelancers who allow a long-time client a short grace period on an invoice are practicing a version of the lista. A small clinic that lets a known patient settle a bill later rather than turning them away is doing the same. Even community-based buy-and-sell groups, where sellers extend credit to familiar buyers within a trusted circle, are an online translation of the same neighborhood logic.
The businesses that tend to succeed with these arrangements share a common discipline: they extend flexibility selectively, based on an actual relationship or track record, not indiscriminately to anyone who asks. The sari-sari store owner does not extend lista to a stranger who has never bought from them before. The trust has to be earned in both directions before the credit is extended.
The Limits of Trust-Based Commerce
None of this means informal trust should replace sound business practice. The lista system works at small scale, within tight communities, where reputational consequences are real and immediate. It becomes fragile when stretched too far — when store owners extend credit to too many people, when amounts grow too large, or when the personal relationship that anchors the arrangement weakens.
The same caution applies to any business borrowing this logic. Flexibility without boundaries becomes exposure. The lesson is not to abandon structure, but to recognize that structure built on top of genuine trust tends to outperform structure imposed without it.
The Larger Point for Philippine Business
The sari-sari store notebook rarely gets discussed in business strategy conversations, yet it quietly explains a great deal about how commerce actually functions in the Philippines. Consumers here are not simply price-driven or brand-driven. They are relationship-driven, and they extend trust the way that notebook extends credit — carefully, incrementally, and based on a track record rather than a pitch.
Businesses that understand this, whether they are running a neighborhood store or a growing company, tend to build something sturdier than a single sale. They build the kind of standing that, like the names in that worn notebook, gets carried forward long after the transaction itself is forgotten.